MoneyLion: Banking & Cash Back

Screenshots
Details
- Rating
- 40.48K reviews
- Version
- 7.142.0
- Developer
- MoneyLion Inc.
Analysis by Norviv
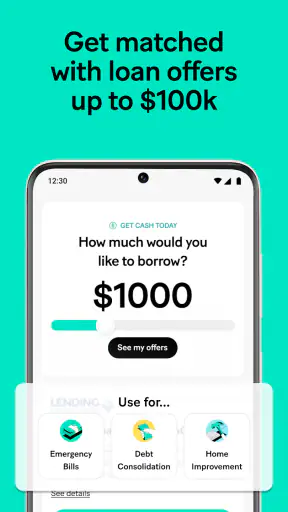
I think a money app is most useful when it helps people make clearer decisions, not when it tempts them to treat borrowing or rewards as free money. That distinction matters with MoneyLion: Banking & Cash Back, which brings several kinds of financial services together under one roof. I would consider it as a possible hub for someone who wants to explore banking, cash-back offers, cash advances, and personal-loan options, while keeping in mind that each service has its own terms and suitability.
Using MoneyLion in a Household
I find a shared-device setup calls for a little more care than the app’s all-in-one convenience might suggest. Before opening MoneyLion around someone else, I’d decide what can be viewed and keep account access with the person responsible for it. That boundary makes it easier to discuss household choices without confusing shared expenses with private financial information.
One phone, more than one person
A shared household can make a multi-purpose finance app sound appealing: one person may be looking for everyday banking, while another wants to compare borrowing options or keep an eye on spending. The practical value is having these topics in one app rather than switching between unrelated services. But that convenience does not make it a shared household account or a family money-management tool. I would treat it as an individual financial app unless the account arrangements clearly say otherwise.
For example, imagine one partner checking whether a purchase might qualify for cash back while the other is reviewing a personal-loan offer. Those are separate financial decisions, even if they concern the same household budget. Before putting someone else’s financial details or account access into the picture, I would agree who owns the account, who is allowed to use the device, and what information should remain private. A shared phone is not the same thing as shared authorization.
Keep account boundaries clear
MoneyLion is a finance app from MoneyLion Inc., and the range of services it brings together makes a little planning worthwhile before signing up. I would first decide what I actually want from it: cash-back discovery, banking, a cash advance, or a loan offer. That helps avoid opening an account simply because the app presents multiple options in one place. It also gives me a sensible way to judge whether the app is useful after the initial curiosity wears off.
For a household, the key boundary is between looking at an offer and committing to a financial product. A loan or advance should be assessed against the person who would be responsible for it, not treated as a casual household feature. I would read the relevant terms and costs before proceeding, and compare them with alternatives that I already understand. A convenient screen can shorten the search, but it cannot decide whether borrowing is affordable.
There is another useful boundary: not every service in a financial app needs to become part of your routine. If you only want to browse cash-back opportunities, you can judge that function on its own rather than assuming you should also use banking or borrowing products. For a more focused experience, a dedicated bank app or rewards service may be easier to understand. MoneyLion’s appeal is breadth; the trade-off is that breadth asks the user to be deliberate.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Coordination without assuming family tools
When people share household expenses, the app itself does not replace a conversation about who pays what. I would use a separate household budget or a simple agreed routine to track shared bills, then use a personal finance app for the individual account holder’s own decisions. That avoids confusing one person’s cash advance or loan offer with money that belongs to both people.
A practical approach is to agree on a check-in before making a borrowing decision: what expense is being covered, when repayment is expected, and what happens if the household budget changes? This is especially useful when an urgent bill makes a fast-cash option look attractive. Comparing the offer with a bill extension, savings, or another source of funds can prevent a quick choice from becoming an expensive one. The right answer depends on the actual terms and the household’s ability to repay.
I would also avoid passing a logged-in device around as a substitute for individual access. Financial information deserves privacy, and a person who can open an app may be able to see more than the item everyone intended to discuss. If the household needs shared visibility, choose an arrangement designed and authorized for that purpose rather than assuming a personal account provides it.
Age, trust, and financial confidence
The app’s content rating is Everyone, but that is not the same as a recommendation that children should manage financial products. I would keep adult decisions about bank services, advances, and loans with the adults responsible for them. A younger family member can learn about budgeting in age-appropriate ways without being given access to another person’s financial account or encouraged to borrow.
For an adult who is new to digital finance, the broad selection may be helpful or overwhelming depending on what they need. I would start with one goal and take time to understand each screen and offer rather than tapping through every prompt. If a term is unclear, pause and look it up before proceeding. Trust in a finance app should come from understanding what you are agreeing to, not merely from a polished interface or the presence of familiar services.
MoneyLion is free to install, but that does not mean every financial service offered through it is cost-free. The distinction is important: an app’s download price and the terms of a financial product are separate things. I would check any applicable fees, rates, repayment conditions, eligibility requirements, and consequences before accepting an offer. This is a basic but valuable habit for any app that presents borrowing choices.
What it does well, and where alternatives may fit
MoneyLion’s main advantage is consolidation. Instead of searching separately for a banking app, a cash-back destination, and borrowing offers, a user can explore several financial needs in one place. That can be useful for someone who wants to compare possibilities without beginning with a long list of separate apps. The company behind it, MoneyLion Inc., has been developing the app since its release on May 19, 2016, and its current version is 7.142.0.
The alternative is a more specialized setup. A person who mainly wants a checking account may prefer comparing bank apps on account features and service terms. Someone who only wants rewards may find a dedicated cash-back service less distracting. For borrowing, comparing offers directly and evaluating the full repayment cost may be more important than convenience. I would choose MoneyLion when having these options together is genuinely useful, not just because an all-in-one app seems automatically better.
There is also a discipline trade-off. Multiple financial options can make it easier to notice a service, but visibility is not a reason to use it. I would decide on a purpose before browsing and return to that purpose when weighing offers. If the app starts to feel like a menu of products rather than a tool for a specific need, stepping back and using a simpler alternative may be the wiser choice.
Who is likely to get the most from it?
I see the strongest fit for adults who are comfortable reviewing financial terms and want to explore several services from one app. Someone interested in cash back who is also comparing banking or borrowing options may appreciate having those needs gathered together. It could also suit a person who is willing to spend time understanding which features are relevant rather than expecting the app to make financial decisions for them.
I would be more cautious if you need a straightforward account and do not want to encounter borrowing offers, if you prefer keeping each financial relationship separate, or if you are not confident evaluating loan costs. It is also not the answer to shared household budgeting by itself. In those situations, a dedicated bank, a purpose-built budget method, or direct conversations about bills may be a better fit.
One useful test is to ask what job you want the app to do this month. If the answer is specific—such as comparing a cash-back opportunity or reviewing an available financial option—you can assess whether MoneyLion helps with that task. If the answer is simply “manage everything,” narrow it down first. A clear goal makes it easier to notice whether a service is actually useful or merely available.
Everyday decisions require a pause
Consider a household facing an unexpectedly high utility bill. One person might open the app to look at a fast-cash option, while the other checks the budget and upcoming expenses. I would treat that as a starting point for comparison, not an automatic solution. They should examine the offer’s terms, consider how repayment fits alongside rent and other bills, and look at alternatives such as contacting the bill provider or using funds already set aside.
The same deliberate approach applies to cash back. Before changing where or how you shop for a reward, check that the purchase was already planned and that the offer’s conditions make sense. A reward should not encourage extra spending that outweighs its value. This is a small workflow, but it turns cash back into a possible benefit rather than a reason to buy something unnecessary.
For borrowing, I would write down the amount needed, the repayment date or schedule, and the likely total cost before accepting anything. If those details are difficult to understand, that is a reason to pause, not a reason to guess. An app can make an option easy to find; the responsibility for deciding whether it fits remains with the borrower.
How I would judge it over time
Rather than evaluating a finance app by how many features it displays, I would check whether it helps me make a specific decision with less confusion. After trying a relevant service, ask whether it saved time, made costs easier to compare, or helped keep an intended task organized. If not, there is little reason to keep adding financial activity to an app just because it offers more choices.
MoneyLion has an average rating of 4.6 from around 207,000 ratings, and it has been installed over 5 million times. Those figures suggest that many people have tried it, but they cannot tell me whether a particular account, offer, or borrowing choice is right for my household. I would still judge the app by the terms of the service I plan to use and by how well it fits my own habits.
At no cost to download and with an Everyone content rating, it is easy to explore, but I would separate that low barrier to entry from the seriousness of financial decisions inside the app. The most useful way to approach it is with a narrow goal, careful reading, and clear account boundaries. Those habits matter even more when a device or household budget is shared.
MoneyLion is a finance app, not a substitute for agreement between people who share expenses. Use it for the individual tasks it suits, keep borrowing decisions personal and informed, and choose a more specialized service if you want one focused function without the wider range. That is the household verdict I would give a friend: worth considering for breadth, but best used with attention rather than treated as a one-tap solution.
First off, signing up was a breeze. The app walks you through the process with clear instructions. You’ll be up and running in no time, ready to explore all the features it offers. It's pretty intuitive, which is great for folks who might be new to managing their finances digitally.
Features That Stand Out
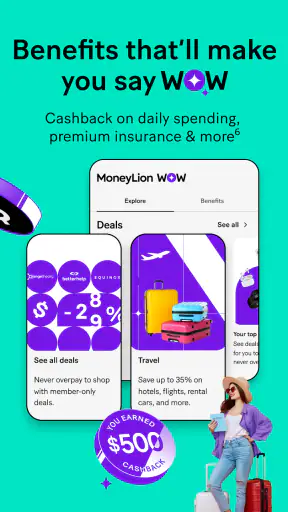
One of the first things I noticed is the sheer number of features packed into MoneyLion. From banking services to investment options, it’s got you covered. I really appreciated the cash back rewards on purchases. Who doesn't love getting a little extra back when spending?
The app also offers a credit builder loan. This is a fantastic tool for anyone looking to boost their credit score. It’s a simple and effective way to work on your credit without diving into complicated financial maneuvers.
User Experience
The user interface is clean and modern. Everything is laid out logically, making it easy to find what you need. I found the budgeting tools particularly useful. They allow you to track your spending and savings effortlessly. Plus, the financial tips and insights are a nice touch, helping you make informed decisions.
Did I mention the alerts? You’ll never miss a payment or overdraft again. The app notifies you of important transactions, keeping you on top of your finances at all times.
Security and Connectivity
Let’s talk security, because hey, it’s your money we’re dealing with. MoneyLion uses advanced encryption to protect your data. I felt secure knowing my information was safe. The connectivity with other financial accounts is seamless too, allowing you to see all your financial data in one place.
Final Thoughts
All in all, MoneyLion: Banking & Cash Back is a fantastic tool for anyone looking to take control of their finances. Whether you're trying to save, invest, or simply manage your daily spending better, this app has something for you. It’s like having a financial advisor, bank, and rewards program all rolled into one.
If you’re curious about enhancing your financial game, give it a whirl. I found it extremely helpful, and I bet you will too. Now, go ahead and download it – your wallet might just thank you!
Frequently Asked Questions
01What features does MoneyLion offer to its users?
MoneyLion provides a comprehensive suite of financial tools, including mobile banking, credit building loans, investment opportunities, and cashback rewards. Users can also access financial tracking tools and personalized advice to manage their finances effectively. This all-in-one platform aims to simplify money management for users by combining essential financial services in one app.
02Is MoneyLion secure for online banking and transactions?
Yes, MoneyLion implements robust security measures to protect user data and transactions. The app uses bank-level encryption and multi-factor authentication to ensure user information is secure. Additionally, MoneyLion is a member of the FDIC, which means users' deposits are insured up to $250,000, providing an extra layer of security for their funds.
03How does the credit building loan work in MoneyLion?
MoneyLion offers credit builder loans designed to help users improve their credit scores. When users take out a loan, the funds are held in a secured account while they make monthly payments. These payments are reported to major credit bureaus, helping to build their credit history. Once the loan is paid off, users can access the full amount of the loan.
04What are the potential drawbacks of using MoneyLion?
While MoneyLion offers several benefits, users should be aware of potential drawbacks. Some users may find the membership fees for certain features and services to be a downside. Additionally, the app's financial advice is generalized and might not replace personalized advice from a financial advisor. It's important to assess whether the app's offerings align with individual financial goals.
05Can I earn cashback rewards through MoneyLion?
Yes, MoneyLion offers cashback rewards through its debit card program. Users can earn cashback on everyday purchases at participating retailers. The cashback is automatically credited to their account, providing an easy way to save money on regular expenses. This feature is a highlight for users looking to maximize their spending efficiency and get more value from their transactions.


